Table of Contents
- Introduction: The Historic Friction of Month-End Bank Reconciliation
- The Architectural Pipeline: Direct Bank Integration Protocols
- Algorithmic Matching Mechanics: How Automated Reconciliation Works
- De-Aggregating Merchant Settlements and Payment Gateway Fees
- Comparison Matrix: Manual vs. Automated Bank Reconciliation
- Exception Management: Handling Unmatched Items and Bank Fees
- Corporate Cash Visibility and Fraud Prevention
- Frequently Asked Questions About Automated Bank Reconciliation
- Conclusion: Accelerating Enterprise Financial Velocity
Introduction: The Historic Friction of Month-End Bank Reconciliation
For generations of corporate accountants, the arrival of the monthly bank statement signaled the start of an exhausting, high-stress ritual. Armed with yellow highlighters, paper printouts, and sprawling Excel spreadsheets, corporate accounting teams spent days manually cross-referencing thousands of line-item bank debits and credits against internal general ledger cash records. Outstanding checks had to be identified, merchant processor fees calculated, wire transfer fees traced, and deposits in transit accounted for.
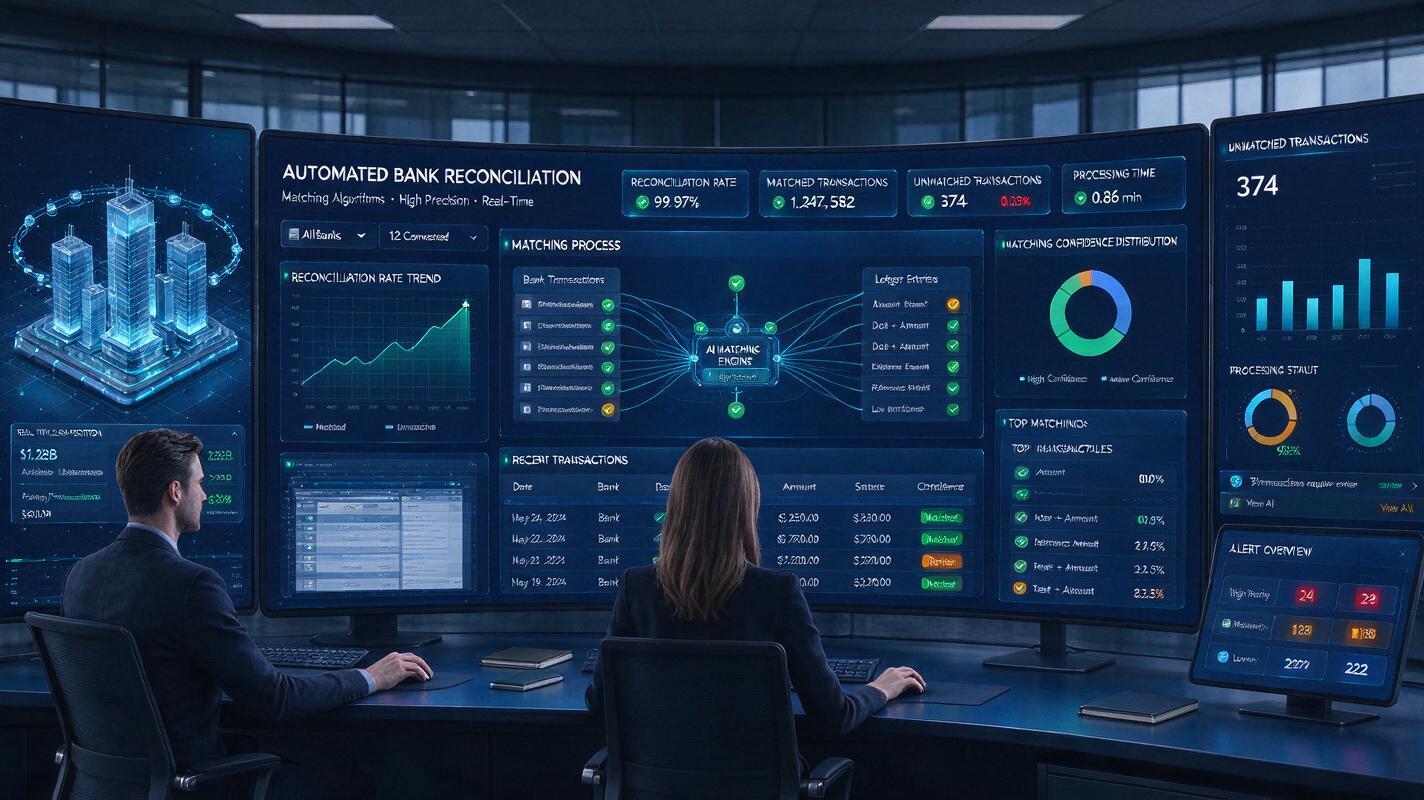
In modern multi-subsidiary, multi-currency enterprises, this manual reconciliation paradigm is completely broken. High-volume business models—such as direct-to-consumer e-commerce, multi-store retail, omnichannel distribution, and global SaaS—generate tens of thousands of electronic transactions daily. Bank deposits arrive as aggregated net settlements from payment processors like Stripe and PayPal, minus variable interchange fees. Foreign operating subsidiaries maintain accounts across dozens of regional banking institutions.
Attempting to reconcile this transactional deluge manually creates severe operational gridlock. The monthly financial close stretches across two to three weeks, corporate controllers operate with stale cash visibility, and internal fraud or bank errors go undetected for thirty days or more.
Modern automated bank reconciliation erp engines dismantle this bottleneck. By establishing direct host-to-host banking feeds and leveraging rule-based matching algorithms, enterprise software matches over ninety-five percent of cash transactions automatically, reducing close cycles from weeks to hours.
This comprehensive guide analyzes the architecture of automated bank feeds, algorithmic matching rules, merchant settlement de-aggregation, and exception governance.
The Architectural Pipeline: Direct Bank Integration Protocols
Automated reconciliation begins with the secure, touchless ingestion of corporate banking data. Modern ERP suites eliminate manual CSV or BAI2 file downloads through automated connectivity protocols:
1. Host-to-Host (H2H) Secure SFTP Feeds:
The traditional enterprise gold standard for large corporations. Corporate treasury establishes dedicated, encrypted Secure File Transfer Protocol (SFTP) pipelines directly with major global financial institutions (such as JPMorgan Chase, Bank of America, Citi, or HSBC). Every morning at 2:00 AM, the bank deposits standardized electronic statement files—such as BAI2, MT940, or ISO 20022 XML formats—into a secure server directory, which the ERP automatically ingests and parses.
2. Open Banking and Real-Time Financial APIs:
Leveraging modern financial API networks (such as Plaid, Yodlee, or direct proprietary bank REST APIs), the ERP establishes bi-directional authenticated connections with commercial banks. Rather than waiting for overnight batch statements, the ERP retrieves intraday account balances and cleared transaction streams in real time.
3. Automated Data Normalization and Parsing:
Bank statement data is notoriously messy. A single wire transfer may contain fragmented alphanumeric reference codes in payment description fields. The ERP parsing engine normalizes these data streams, mapping transaction dates, value dates, bank reference codes, counterparty names, and monetary values into standardized database tables. To understand broader cash management, review our guide to core ERP financial management module capabilities.
Algorithmic Matching Mechanics: How Automated Reconciliation Works
Once bank statement lines and internal general ledger cash transactions reside within the same database environment, the ERP automated reconciliation engine executes a hierarchical series of matching passes:
Advertisement
Pass 1: Exact One-to-One Cryptographic Matching
The system executes high-confidence matching rules. If a bank statement line matches an internal GL transaction exactly across three primary parameters—Transaction Date (within a configured variance window, e.g., +/- 2 days), Check / Reference Number, and Exact Monetary Amount—the system immediately marks both records ‘Matched and Cleared’ without requiring human review.
Pass 2: One-to-Many and Many-to-One Batch Matching
Physical banking reality frequently diverges from internal accounting records:
– Many-to-One (Batch Deposits): A retail store or branch office deposits thirty individual customer cash and check receipts into the bank at the end of the day. The bank statement displays a single aggregate deposit of $15,420, while the internal ERP subledger contains thirty individual payments. The ERP matching engine aggregates internal receipts sharing the same deposit slip ID and matches the batch against the single bank line.
– One-to-Many (Disbursement Batches): A corporate accounts payable department executes an electronic ACH payment run containing forty vendor bills. The bank statement debits a single lump-sum ACH total, while the AP ledger reflects forty individual payments. The matching engine matches the batch header total against the bank debit. For AP workflow integration, review our guide on automated accounts payable ERP workflows.
De-Aggregating Merchant Settlements and Payment Gateway Fees
For e-commerce and retail enterprises, payment processor settlements represent the most complex reconciliation challenge. Payment processors (such as Stripe, Shopify Payments, Adyen, and PayPal) do not deposit gross sales proceeds into corporate bank accounts. Instead, they batch hundreds of daily transactions, deduct variable processing fees (e.g., 2.9% + $0.30 per swipe), and deposit the net settlement two days later.
How Enterprise ERP Resolves Merchant Gateways:
– Gateway Settlement API Ingestion: The ERP connects via API directly to the payment gateway to ingest granular transaction settlement reports.
– Automated Split-Entry Posting: When a net deposit of $9,700 arrives at the bank, the ERP cross-references the gateway report. The system automatically creates a journal entry:
– Debit: Operating Cash Account ($9,700)
– Debit: Merchant Processing Fee Expense ($300)
– Credit: Undeposited Merchant Clearing Account ($10,000)
– Instant Clearance: Both the bank line and internal ledger clearing lines are matched and reconciled instantly, eliminating days of manual fee calculations. To evaluate foreign currency settlements, see our guide on multi-currency ERP accounting and global consolidations.
Comparison Matrix: Manual vs. Automated Bank Reconciliation
The following analytical matrix compares operational key performance indicators between traditional manual reconciliation and automated ERP bank reconciliation:
| Operational Metric | Manual Spreadsheet Reconciliation | Automated ERP Bank Reconciliation |
|---|---|---|
| Reconciliation Frequency | Monthly (after physical bank statements arrive). | Daily continuous automated reconciliation. |
| Auto-Match Percentage | 0% (Every line item verified manually). | 92% to 98% of clean transactional volume. |
| Month-End Close Duration | 8 to 15 business days. | 2 to 4 business days. |
| Error & Discrepancy Detection | 30 to 45 days after transaction occurrence. | Within 24 hours of bank settlement. |
| Audit Trail Documentation | Paper binders and disconnected Excel files. | Immutable digital system logs linking bank IDs to GL. |
Exception Management: Handling Unmatched Items and Bank Fees
In any automated reconciliation environment, a small percentage of transactions (typically 2% to 8%) fail initial algorithmic matching rules. These exceptions represent bank service charges, unexpected wire fees, unauthorized debits, or customer payments received without invoice reference data.
Modern ERP suites streamline exception resolution through intelligent workflow queues:
– Automated Journal Entry Templates: For routine bank fees (such as monthly account maintenance fees or incoming wire surcharges), the accounting clerk clicks a single button to execute a pre-configured template, creating the balancing debit to Bank Fee Expense and clearing the line in seconds.
– Fuzzy Logic Matching Recommendations: If an invoice reference number contains a slight typo (e.g., ‘INV-10928’ vs ‘INV-1092B’), the system’s machine learning engine suggests the probable match with a percentage confidence score.
– Suspense Account Quarantine: Unidentified deposits are automatically posted to a temporary clearing or suspense account, triggering an automated task for the accounts receivable team to investigate without holding up the month-end cash close. To review data migration architectures, explore our guide on legacy ERP data migration strategies.
Corporate Cash Visibility and Fraud Prevention
Transitioning to daily automated bank reconciliation delivers profound strategic benefits beyond accounting efficiency:
Real-Time Treasury Liquidity:
Corporate controllers and CFOs no longer operate in the dark regarding actual cash positions. Instead of waiting for month-end reports, executive dashboards display verified cash balances across all global operating entities every morning, enabling treasury teams to optimize short-term investment yields and minimize unnecessary line-of-credit interest expenses.
Immediate Fraud and Cybercrime Detection:
If a fraudulent check is presented or a cybercriminal executes an unauthorized ACH debit, manual reconciliation teams rarely discover the theft until weeks later, well past statutory bank reporting windows. Automated daily reconciliation flags unrecognized bank debits within twenty-four hours, empowering finance leaders to notify banking partners and recover stolen funds immediately.
Frequently Asked Questions About Automated Bank Reconciliation
What file formats are used for automated bank feeds in enterprise ERP?
Standard formats include BAI2 and BTRS (popular in North America), MT940 and MT942 (global SWIFT formats), and modern ISO 20022 XML formats (camt.053 for statements, camt.052 for intraday reporting).
How does automated reconciliation handle merchant processing fees?
The ERP connects directly to payment gateways to ingest fee settlement files, automatically splitting the gross sale from interchange fees and posting balancing journal entries directly to expense accounts.
What is a continuous close in corporate accounting?
A continuous close is a modern operational practice where transactions, bank reconciliations, and intercompany balances are matched daily rather than concentrated into a frantic multi-week period at the end of the month.
Can an ERP automatically reconcile foreign currency bank accounts?
Yes. The ERP maintains subledgers in the bank account’s native currency while executing automated currency revaluations to corporate reporting currency using daily spot exchange rates.
Furthermore, enterprise organizations must implement disciplined governance controls across software evaluation frameworks. By establishing clear cross-departmental accountability, continuous stakeholder alignment, and structured change management protocols, corporate leadership ensures that technological investments directly advance broader operational objectives. This strategic alignment mitigates implementation friction, protects capital allocation, and maximizes measurable business outcomes throughout the entire organizational lifecycle.
In addition, modern cloud enterprise architectures require ongoing optimization to maintain peak performance as transaction volumes expand. Cross-functional committees should conduct periodic architectural reviews, evaluate emerging integration capabilities, and refine role-based security configurations. Maintaining this proactive operational posture ensures sustained scalability, regulatory compliance, and enduring competitive advantage across evolving market sectors.
Moreover, establishing standardized performance telemetry allows enterprise operations teams to detect systemic bottlenecks before they impact customer fulfillment. Continuous data analysis reveals opportunities for incremental process automation, supplier SLA enforcement, and working capital optimization, ensuring that technology investments compound in value over time.
Finally, the convergence of automated workflow orchestration and real-time business intelligence creates an agile foundation for future market expansion. Organizations that cultivate deep digital fluency across operational departments achieve superior customer satisfaction scores, lower operating overhead, and greater strategic agility in volatile economic conditions.
To sustain.
Conclusion: Accelerating Enterprise Financial Velocity
Bank reconciliation is the vital audit bridge connecting internal financial records with external banking reality. Continuing to manage this mission-critical function through manual spreadsheets is an operational handicap that wastes valuable talent, delays corporate decision-making, and exposes the organization to fraud.
By deploying automated bank reconciliation within an enterprise ERP, organizations replace tedious manual checking with high-speed algorithmic precision. Daily direct bank feeds, intelligent multi-pass matching, and automated fee de-aggregation transform month-end close from an agonizing ordeal into a routine, push-button verification.
Freeing your accounting team from manual data entry empowers them to focus on high-impact financial analysis, accelerating enterprise velocity and providing leadership with the real-time cash clarity required to win in today’s competitive global economy.
Furthermore, enterprise organizations must implement disciplined governance controls across software evaluation frameworks. By establishing clear cross-departmental accountability, continuous stakeholder alignment, and structured change management protocols, corporate leadership ensures that technological investments directly advance broader operational objectives. This strategic alignment mitigates implementation friction, protects capital allocation, and maximizes measurable business outcomes throughout the entire organizational lifecycle.
In addition, modern cloud enterprise architectures require ongoing optimization to maintain peak performance as transaction volumes expand. Cross-functional committees should conduct periodic architectural reviews, evaluate emerging integration capabilities, and refine role-based security configurations. Maintaining this proactive operational posture ensures sustained scalability, regulatory compliance, and enduring competitive advantage across evolving market sectors.